Retirement planning, with you in mind

Make retirement the best time of your life.

More time for the people and possibilities you love. Explore annuity strategies that help turn your savings into a plan for the life ahead.

Personal guidance · In person or online · No pressure to purchase

A real person. A thoughtful plan.
Your GICROSOFT annuity specialist
Good planning starts with listening. Your goals, your questions, your pace.
Income for the long runExplore lifetime income options
Clarity before commitmentUnderstand benefits and tradeoffs
Learn in your languageEnglish · Mandarin · Cantonese
Why I believe annuities deserve a closer look

Protect your foundation.
Plan for a longer future.

Two ideas shape my approach: give different parts of your money different jobs, and prepare for a life that may last longer than today’s assumptions.

01 / The barbell approach

A protected base.
Room for growth.

In a barbell-style portfolio, I see a fixed indexed annuity as a potential part of the conservative side: principal protected from index declines, with the opportunity to capture a portion of market growth. That can complement separate investments chosen for growth.

Interest credits follow the contract’s limits. Insurer strength, withdrawal terms, and applicable charges still matter.

Watch my shortRetiring into a market drop: sequence of returns riskWatch on YouTube Watch my short刚退休就遇到市场下跌:收益顺序风险Watch on YouTube Watch my shortAnnuities & the barbell strategyWatch on YouTube Watch my shortAnnuities & the barbell strategyWatch on YouTube How an annuity can fit a barbell strategy
02 / The longevity opportunity

What if your best years
last much longer?

I believe accelerating AI and medical progress could bring a major turning point in human longevity. That possibility makes lifetime income worth exploring today—so your plan is prepared if retirement lasts much longer than expected.

An eligible lifetime-income option shifts the risk of outliving its covered payments to the insurer, subject to contract terms and claims-paying ability. The timing and scale of lifespan gains remain uncertain.

Watch my shortLifetime income & longevity riskWatch on YouTube Watch my shortLifetime income & longevity riskWatch on YouTube Watch my shortAnnuities: preparing income for a longer lifeWatch on YouTube Watch my shortAnnuities: preparing income for a longer lifeWatch on YouTube Plan for the possibility of a much longer life
Strategy options

Different goals.
A thoughtful way forward.

Start with what you want your money to do. We can explore two approaches, then talk through which one fits your retirement timeline.

01 / Income that lasts

Lifetime Income Strategy

Build a dependable income foundation for a retirement that may last longer than you expect. Explore lifetime payments and options for a spouse.

Start here if you’re asking“How can I create income I won’t outlive?”
02 / A shorter commitment

5-Year Flex Strategy

For those who value a shorter commitment: explore a five-year strategy with principal protection, growth potential, and access after the term.

Start here if you’re asking“What if I prefer access after five years?”

Benefits and access depend on the contract. Review withdrawal rules, charges, and any tax consequences before deciding. Request a current illustration privately for personalized figures.

The GICROSOFT approach

Nine ideas. One more confident retirement.

Every first letter spells GICROSOFT—a simple way to remember the questions worth asking about your retirement.

Guaranteed lifetime income

Create income you cannot outlive with an eligible lifetime-income option, subject to the contract’s terms and the insurer’s ability to pay.

Invest with confidence

Look beyond a headline rate. Understand the insurer’s financial strength, the contract, and how the strategy fits your goals.

Compare bonus benefits

See where a bonus applies: to accessible cash value or to an income benefit base. Compare its conditions and tradeoffs.

Reduce market risk

With a fixed indexed annuity, your principal is protected from index declines. Early withdrawals, applicable charges, and the insurer’s ability to pay still matter.

Overcome longevity risk

Technology may extend the horizon of retirement. An eligible lifetime-income option can provide payments you cannot outlive, subject to contract terms and the insurer’s ability to pay.

Support purchasing power

Some income strategies offer growth potential after payments begin. Review how income could increase, while recognizing that increases may not match inflation.

Optimize retirement life

Confidence in income can support lifestyle, family peace of mind, and more freedom in retirement choices.

Family protection

Explore joint lifetime-income and beneficiary options, including how each choice affects payments for you and your family.

Tax-aware planning

A Roth conversion’s taxable value may be substantially lower than the income benefit base (PIV). Review a current, personalized illustration and the tax calculation with your tax professional.

A fresh way to explore

Your next chapter
has more than one soundtrack.

Retirement is about living, too. Listen to an original AI music project or explore everyday money decisions through play.

Listen / An original AI music project

A sound for your golden years.

Original AI-created songs about annuities, retirement, and what comes next. Songs follow your website language. Press play and find your soundtrack.

Listen on YouTube: choose a playlist below.

YouTube loads only when you press play. If playback is blocked, use a playlist link above. Songs are creative content, not individualized financial advice.

Explore the original listening room ↗
Planning beyond the numbers Retirement planning themes: lifetime income, tax-aware choices, and longevity
“The best plan begins with the life you want to live.”

Income. Family. Freedom to look forward.

About GICROSOFT

A personal conversation.
A clearer path ahead.

I specialize in annuities and help people think through income, protection, flexibility, and tax-aware retirement decisions. My approach is simple: listen first, explain clearly, and give you room to decide.

As technology changes what the future may look like, I believe in planning for a longer horizon. Whether you are exploring annuities for the first time or comparing options, we can meet in person or online.

A little more about me: AI, music & making

I also build practical AI side projects and create annuity-inspired music. They are another way to explore ideas and make learning more approachable.

I enjoy 3D printing too. Visit my MakerWorld profile to see what I make. When you schedule a consultation, you can receive a small 3D-printed gift.

Cell / WhatsApp206 753 8819
WeChatxiangyu_cao
Emailinfo@gicrosoft.com
What to expect

Three steps. No pressure.

You do not need all the answers to get started. Bring your questions and we’ll work through them together.

01

Understand your goal

We start with your retirement timeline, family needs, income concerns, and comfort level with guarantees.

02

Compare strategies

We review lifetime income and flexibility options in plain language, including benefits and limitations.

03

Decide with clarity

You receive information and next steps without sales pressure, so you can make a confident choice.

Annuity knowledge & common misconceptions

Good questions.
Clearer retirement choices.

Explore where annuity funding can come from, how retirement-account taxes work, and why a longer life changes the income conversation.

01 Funding & taxes

Do I need extra after-tax cash to buy an annuity?

Not necessarily. Start by reviewing the retirement money you already have. I generally suggest looking at eligible pre-tax retirement funds before committing new after-tax savings. A former employer’s 401(k) may be one source, so “I don’t have spare cash” does not automatically rule out an annuity conversation.

Keep money needed for everyday expenses and emergencies accessible. A rollover is a choice to evaluate, not a requirement.

Watch my short: using pre-tax money ↗Watch my short: using pre-tax money ↗
Can I use a previous employer’s 401(k)?

Eligible pre-tax funds can generally move by direct rollover into a traditional IRA annuity that accepts them, without current income tax. Confirm eligibility with the plan and receiving provider; avoid cashing out first.

Compare keeping the plan, another employer plan, and an IRA—including fees, investments, protections, and withdrawal rules.

Source: IRS rollover guidance.

Is tax planning about paying tax now or later?

Think beyond this year's tax bill. Plan for after-tax income over your lifetime. The question is not simply whether to pay tax earlier or later, but how the timing fits your income needs and tax circumstances across retirement.

Traditional pre-tax retirement withdrawals are generally taxable; qualified Roth IRA withdrawals are tax-free. Having both can give you flexibility over which account you draw from. Compare today's tax rate with plausible future rates, withdrawal needs, and required minimum distributions. A Roth conversion generally adds its taxable portion to income in the conversion year—it is not automatically a tax saving.

An annuity inside an IRA does not add another layer of tax deferral. Evaluate its contractual income benefits separately from the account's tax treatment. Review conversion amounts and withdrawal timing with your tax professional; future tax rates and savings are not guaranteed.

Watch: Tax planning—think lifetime, not just now or later ↗

税务规划不只看今年交多少税,更要看一生能留下多少税后收入。 重点不是一概选择“早交税”或“晚交税”,而是让纳税时点与退休各阶段的收入需求和税务状况相配合。

传统税前退休账户的支取通常需要纳税;符合条件的 Roth IRA 支取免税。同时拥有两类账户,可以增加选择支取来源的灵活性。应比较当前与未来可能的税率、生活支出和最低强制提领(RMD)。Roth 转换中的应税部分通常计入转换当年的收入,因此转换并不自动等于省税。

在 IRA 内购买年金不会增加一层额外的递延纳税优惠。应把年金合同的收入保障与账户税务规则分开评估,并与税务专业人士共同确定转换金额和支取时机;未来税率和节税结果都不是保证。

观看短视频:税务规划,不只看早交或晚交,而是看一生 ↗

Sources: IRS Publication 590-B · SEC Investor.gov.

Does the annuity keep the retirement account’s tax treatment?

An annuity inside a traditional IRA follows traditional IRA tax rules. A qualifying rollover preserves tax deferral; withdrawals are generally taxable, and required-distribution and early-withdrawal rules still apply. IRA and 401(k) rules are not identical. Moving pre-tax money to a Roth account is generally taxable.

The annuity adds no extra layer of tax deferral inside an IRA. Its purpose is its income guarantees and other contract benefits.

Sources: IRS · SEC Investor.gov.

Does that mean after-tax money should never be used?

No. My starting preference is to review suitable pre-tax retirement funds first. An annuity funded outside a retirement account with after-tax savings can still fit some plans, but the tax treatment is different. The right funding source depends on your existing accounts, cash needs, and overall goals.

Is the income benefit base (PIV) the same as cash or a Roth conversion’s taxable value?

No. An income benefit base is used to calculate contractual income benefits; it is not necessarily cash you can withdraw. A Roth conversion’s taxable value may be substantially lower than the PIV. The actual amount depends on the contract valuation and your tax circumstances.

We review current, personalized illustrations privately and confirm the tax calculation with your tax professional.

02 Longevity & protection

Why can the income benefit base be much higher than the cash value?

They serve different purposes—not two separate pots of money. Cash value tracks the contract's account value; the amount available on surrender may be lower after applicable charges and adjustments. An income benefit base is a calculation figure used by certain lifetime-income features, not a balance you can cash out.

The base may grow under its own contractual formula, so it can be much larger than the cash value. A higher base is not the same as a higher investment return. Annual income typically depends on the benefit base and the applicable payout rate, together with the contract's rules.

Income withdrawals can reduce cash value. With an eligible lifetime-income guarantee, covered payments can continue even if that value reaches zero, provided contract conditions are met. Compare guaranteed income, starting age, fees, and access to funds—not just the largest number.

▶ Watch: Cash value vs. income benefit base · 1 min ↗

它们用途不同,并不是两笔可以分别领取的钱。现金值反映合同中的账户价值;实际退保可取金额,还可能扣除适用的费用和调整。收益基数则是某些终身收入功能用来计算给付的数字,不是可以一次性取出的现金。

收益基数可以按照合同单独的公式增长,因此可能明显高于现金值。但基数增长不等于实际投资回报。每年能领取多少,通常由收益基数、适用的领取比例及合同规则共同决定。

开始领取收入后,现金值可能随提款减少。符合条件的终身收入保障,可以在现金值耗尽后继续按合同给付。因此,应一起比较保证收入、开始领取年龄、费用和资金灵活性,而不是只看最大的数字。

▶ 观看:现金值与收益基数的区别 · 约1分钟 ↗
Why is lifetime income insurance—not just another investment?

An insurer pools many lifetimes. You have only one retirement. Across a large group, some people receive payments for fewer years and others for much longer. Pooling longevity risk helps an insurer offer lifetime payments; pricing also reflects investments, expenses, reserves, and other risks—not average life expectancy alone.

Your own plan needs to allow for living beyond the average. Using part of your savings for guaranteed lifetime income can transfer some of the risk of outliving your money to the insurer and help cover basic expenses, while keeping other assets available for flexibility and growth.

The guarantee covers the income specified in the contract, not every future expense. Payment options, withdrawal limits, inflation, and the insurer's claims-paying ability still matter. Ages 95 or 100 are planning scenarios, not predictions.

▶ Watch: The insurance behind lifetime income · 1 min ↗

保险公司面对很多人的寿命,您只有一次退休。在一个大群体中,有人领取的年数较少,也有人领取得更久。通过分担长寿风险,保险公司能够提供终身给付;定价还要考虑投资、费用、准备金和其他风险,而不只是平均寿命。

个人规划需要考虑活得比平均寿命更久的情况。用部分储蓄安排保证终身收入,可以把一部分“人还在、钱先用完”的风险转移给保险公司,帮助覆盖基本生活费,同时保留其他资产的灵活性和增长空间。

保障的是合同约定的收入,并非所有未来开支。领取方式、提款限制、通胀和保险公司的偿付能力仍然重要。95岁或100岁是规划情景,不是对个人寿命的预测。

▶ 观看:年金如何分担长寿风险 · 约1分钟 ↗

Source: SEC Investor.gov.

Why should Asian women pay particular attention to lifetime income?

A longer life can mean more years of retirement expenses. In the CDC’s 2023 U.S. life tables, non-Hispanic Asian women at age 65 had an average remaining life expectancy of 24.1 years, compared with 20.7 years for U.S. women overall at the same age.

That makes lifetime income worth discussing when planning for a long retirement. These are population averages, not a prediction for any individual. Health, family history, existing income, liquidity needs, and contract terms matter; ethnicity or sex alone does not determine whether an annuity is suitable.

Source: CDC/NCHS, United States Life Tables, 2023, Table A (published July 2025).

Watch my short: Asian women & longevity ↗
What if I live longer than expected?

Longevity risk is the possibility of outliving your savings. An eligible lifetime-income option can transfer the risk of outliving its covered payments to the insurer when contract conditions are met. We review payment amounts, starting age, spouse options, and withdrawal rules together.

This does not guarantee that all future expenses will be covered: inflation, changing needs, and the insurer’s ability to pay still matter.

Watch my short: Lifetime income & longevity risk Watch my short: Lifetime income & longevity risk Watch my short: preparing income for a longer life Watch my short: preparing income for a longer life
How can a fixed indexed annuity fit a barbell investment strategy?

A barbell-style approach gives protected capital and growth-oriented investments distinct roles. My view is that a fixed indexed annuity can serve as part of the conservative side: it protects principal from index declines and offers interest linked to a portion of an index’s growth.

It is not an index fund or a cash equivalent. Crediting limits, surrender terms, charges, and insurer risk affect the fit. Keep adequate liquid reserves and consider the overall allocation before deciding.

Watch my short: Annuities & the barbell strategy Watch my short: Annuities & the barbell strategy Watch: Retirement withdrawals & sequence risk ↗观看短视频:退休支取与收益顺序风险 ↗

Product mechanics: FINRA’s indexed annuity guide. The barbell application above is my planning perspective.

Could accelerating technology make lifetime-income planning more important today?

I believe AI and medical progress could put us closer to a major turning point in human longevity. That possibility is a reason to plan today for a retirement that may last much longer.

A near-term leap in human lifespan is not established. Researchers are still developing and validating human trials of interventions targeting aging. I treat longer lives as a planning possibility, not a promised medical outcome.

Lifetime income can address the risk of outliving the payments covered by a contract. Whether to purchase now depends on your goals, age, available terms, and liquidity needs—not on a prediction alone.

Research context: Endpoints for geroscience clinical trials (2022). Income features: SEC annuity guide.

Can a fixed indexed annuity protect me from market declines?

Yes—fixed indexed annuities protect principal from index declines under their contract terms. That protection does not mean cash value can never decrease: withdrawals, applicable charges, and the insurer’s ability to pay still matter. Indexed interest may also be limited by caps, participation rates, or other terms.

How do lifetime income and five-year flexibility differ?

The lifetime-income approach focuses on payments that can continue for life. The five-year approach focuses on a shorter commitment and access after the term. We compare the tradeoffs, withdrawal conditions, and how much money you need to keep accessible.

Compare the two strategies ↑

03 Getting started

Do I need to be ready to buy an annuity?

No. A free consultation is a chance to ask questions, explore your retirement goals, and understand the options. There is no pressure to purchase.

Can I see numbers for my own situation?

Yes. Ask for a current, personalized illustration during a private consultation. Values and available terms can change, so we review the applicable figures and contract details together.

What should I bring to our conversation?

Your questions, retirement timeline, income goals, and any flexibility needs are a useful starting point. Please don’t send account numbers, Social Security numbers, or other sensitive financial details through the contact form.

COMMUNITY CARE / MADE WITH A 3D PRINTER

Free 3D prints for people nearby.

Useful little things and playful ideas, printed and shared for free.

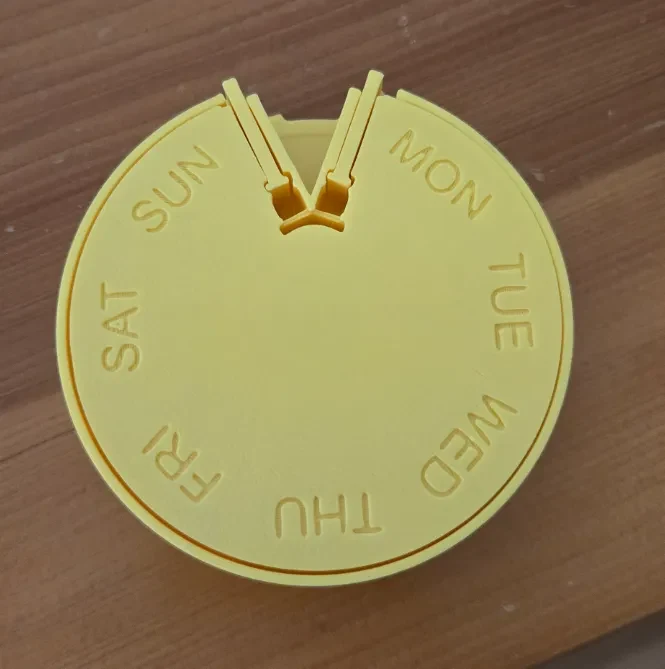
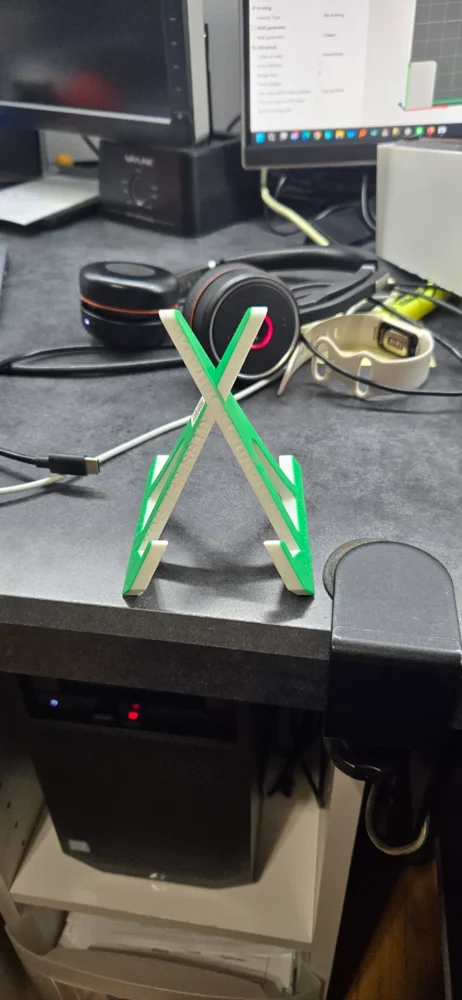
Need a bag clip, phone stand, pill box, or a little puzzle? I would be happy to print one for you. This is open to anyone nearby—individuals, families, and organizations alike. If you are in my area, we can arrange for me to bring it to you.

Explore the 15 projects, then tell me the item name, your city or neighborhood, approximate quantity, and how to contact you. We will confirm printing and delivery together.

Browse all 15 free-print ideas ↗

Contact me for a free print ↗

实用的小物、有趣的玩具,免费打印送给您。

需要封口夹、手机支架、药盒,或一个益智小玩具吗?我很乐意为您打印。任何在附近有需要的人都可以联系我,个人、家庭和机构都欢迎。如果您在我周围,我们可以安排打印后送给您。

先浏览这15个项目,再告诉我物品名称、您所在城市或附近区域、大致数量和联系方式。我们一起确认打印和送达安排。

浏览全部15个免费打印项目 ↗

联系我免费打印 ↗

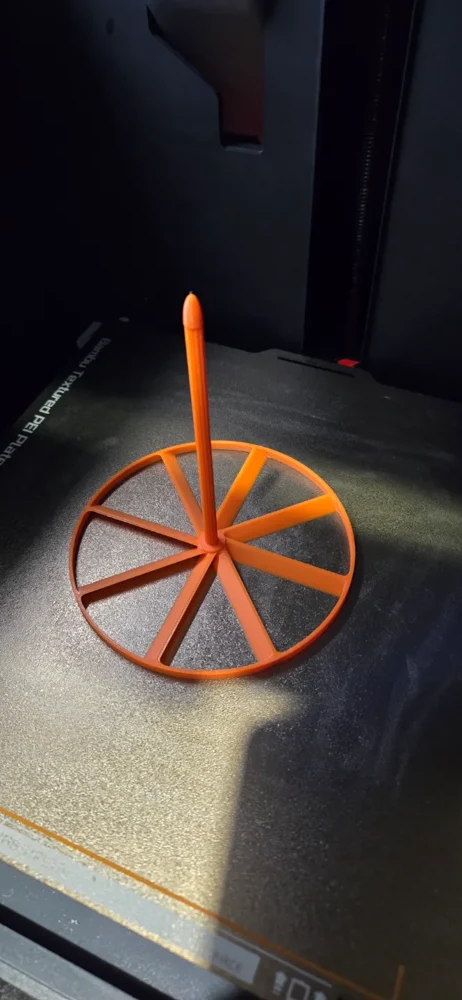
Travel pill boxPhone standBamboo dragonfly rotor
Contact GICROSOFT

Start with a simple message.

Tell me what’s on your mind and how to reach you. I’ll reply personally, and we can take it from there.

You can leave your message in English or Chinese. External forms, videos, and PDFs retain their original content language.

表单字段对照:Name=姓名;Email=电子邮箱;Phone=电话;Message=留言。您可以直接填写中文。

  • A free, introductory conversation
  • Meet in person or online
  • No pressure to purchase

Prefer to call? 206 753 8819

Open form in a new tab